- Declining Balance-to-Loan Ratios Push Consumer Credit Leverage to a 12-Month Low
- Serious Delinquencies Remain Contained as Consumers Continue to Manage Credit Obligations
- Consumer Credit Tier Distribution Remains Stable Despite Gradual Shift from Prime to Nearprime
SAN FRANCISCO — October 26, 2026 — In September 2026, consumer credit remained resilient despite early-stage payment pressure, according to the latest edition of CreditGauge™ from VantageScore. Balances were stable, and credit card utilization remained below 2026 levels. The average VantageScore 4.0 credit score remained at 701, continuing a trend of steady consumer credit scores over the last year.
Consumers have been able to manage their debt effectively and responsibly, as evidenced in strong credit balances and lower utilization,” said Atif Mirza, EVP and Chief Digital and Insights Officer at VantageScore. “Even as early delinquencies remain an area to watch, consumers appear to be navigating this economic environment.
Watch CreditGauge LIVE for additional key insights from the September 2026 edition of CreditGauge that include:
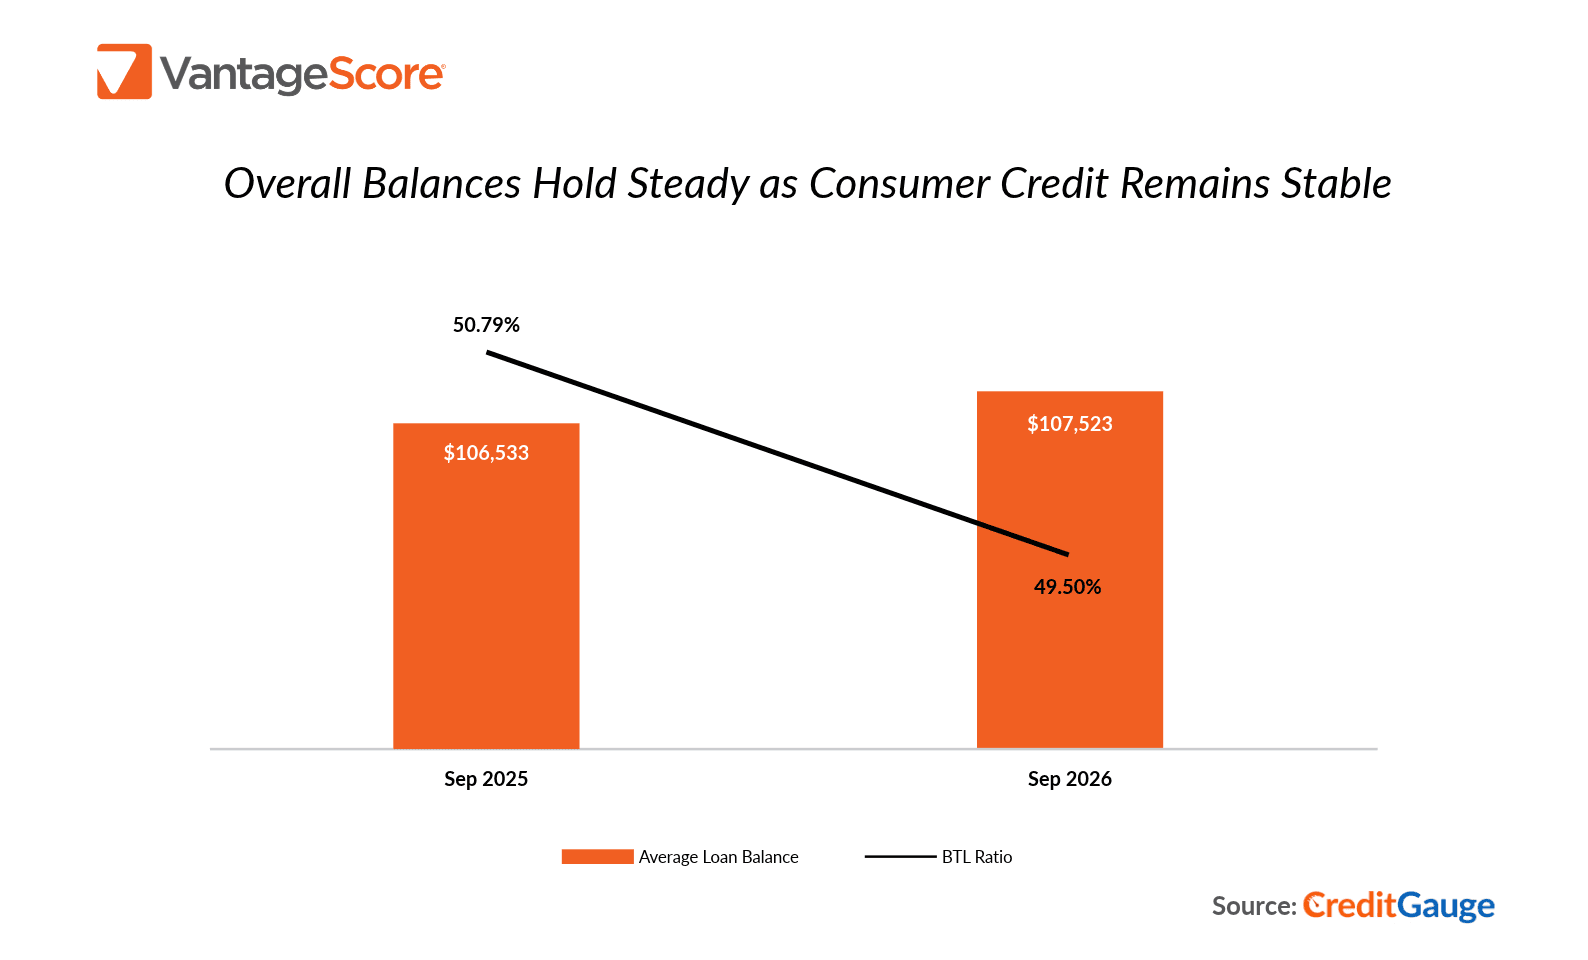
CONSUMER BALANCES HOLD STEADY, OVERALL LEVERAGE FALLS TO A 12-MONTH LOW: In September 2026, the average consumer balance remained near $107.5K, essentially unchanged from August 2026 and $990 above September 2025. The overall balance-to-loan ratio (BTL) declined from 49.60% to 49.50% month-over-month and remained 1.29% below its year-ago level of 50.79% in September 2025. Stable overall balances, combined with a lower balance-to-loan ratio, suggest that consumers continued to pay down debt relative to their original loan amounts, indicating stable borrowing conditions.
SERIOUS DELINQUENCIES REMAIN CONTAINED AS CONSUMERS CONTINUE TO MANAGE CREDIT OBLIGATIONS: In September 2026, late-stage, or 90-119 days past due (DPD), delinquencies remained relatively stable at 0.23% and just 1 basis point above September 2025. While early-stage (30-59 DPD) delinquencies increased month-over-month to 1.15%, they remained only 2 basis points above year-ago levels. The relatively steady year-over-year delinquency rates suggest that consumers continue to manage their credit obligations despite ongoing economic pressures.
CONSUMER CREDIT TIER DISTRIBUTION REMAINS STABLE DESPITE GRADUAL SHIFT FROM PRIME TO NEARPRIME: The average VantageScore 4.0 credit score held steady at 701 in September 2026, reflecting continued stability in overall consumer credit quality. Over the past two years, the share of VantageScore Prime consumers declined modestly from 33.3% to 32.5%, while VantageScore Nearprime increased from 17.4% to 18.0% and VantageScore Subprime edged up from 18.4% to 18.7%. The limited changes in credit-tier distribution indicate that consumer credit quality remains steady amid the current economic environment.
Follow VantageScore on LinkedIn and YouTube to watch CreditGauge LIVE, a monthly video series featuring our latest insights on consumer credit data and analysis.
CreditGauge is a monthly analysis highlighting the overall health of U.S. consumer credit. To download this month’s full CreditGauge report, visit the VantageScore website.
About VantageScore CreditGauge™
CreditGauge is provided both as a monthly analysis to industry stakeholders as well as through a series of interactive tools at VantageScore.com, which also includes Inclusion360®, RiskRatio™ and MarketGain™. Stakeholders can use the tools to execute additional queries on credit metrics and compare current levels to a pre-pandemic timeframe, starting with January 2020. CreditGauge solely represents the views and analysis of VantageScore and does not necessarily reflect or represent the views of the Nationwide Consumer Reporting Agencies (NCRAs) - Equifax, Experian, and TransUnion.
About VantageScore®
VantageScore is the fastest-growing credit scoring company in the U.S., and is known for the industry’s most innovative, predictive and inclusive credit score models. In 2024, usage of VantageScore increased by 55% to hit 42 billion credit scores. More than 3,700 institutions, including nine of the top 10 U.S. banks, use VantageScore credit scores and digital tools to provide consumer credit products or generate greater insights into consumer behavior. The VantageScore 4.0 credit scoring model scores 33 million more people than traditional models. With the FHFA allowing the immediate use of VantageScore 4.0 for Fannie Mae and Freddie Mac guaranteed mortgages, the company is also ushering in a new era for mortgage lending.
VantageScore is an independent joint venture company owned by Equifax, Experian and TransUnion.